Reverse mortgage guide · Paying for long-term care
Using a Reverse Mortgage to Pay for Long-Term Care
A reverse mortgage can fund in-home care, home modifications or a paid caregiver, but it works best for care at home; 12+ months in a facility makes the loan due.
- Sourced from HUD, CFPB, FTC & NCOA
- 2026 FHA limit: $1,249,125
- No cost · No obligation · No credit check
Most people would rather get care in their own home than move. For a homeowner 62 or older with substantial equity, a federally insured reverse mortgage (a HECM) can turn part of that equity into money for care without adding a monthly mortgage payment. This page explains what it can pay for, where it falls short, and how families can plan around it.
Key takeaways
- HECM proceeds can be used for any purpose, including in-home aides, adult day care, a paid family caregiver, home modifications and long-term care insurance premiums.
- Living in a nursing home or other facility for more than 12 consecutive months ends your principal residence and can make the loan due, unless a co-borrower or eligible non-borrowing spouse still lives there.
- A line of credit is often the most flexible way to pay for care needs that are unpredictable; tenure payments suit steady, ongoing costs.
- Loan proceeds are not generally treated as taxable income and do not affect Social Security or Medicare, but money kept past the month received can count against Medicaid or SSI limits.
- Bring adult children into the conversation early, and talk to a HUD-approved counselor before you apply.
Can you use a reverse mortgage to pay for long-term care?
Yes. A HECM can be used for any purpose, and many homeowners use it to pay for care that lets them stay at home. It is much less suited to paying for a long stay in a nursing home or assisted living facility.
A home equity conversion mortgage (HECM) lets homeowners 62 and older borrow against their home without making monthly principal and interest payments. You keep title to the home. The loan is repaid later, usually when the last borrower sells, moves out permanently or dies (CFPB). If you are new to the product, start with our overview of reverse mortgages and how a reverse mortgage works.
The National Council on Aging’s federally approved booklet on reverse mortgages is titled ‘Use Your Home to Stay at Home’, which sums up the best use case: turning home equity into the support that lets you keep living where you are (NCOA).
- In-home care: personal care aides, home health help not covered by insurance, housekeeping and meal support.
- Home modifications: ramps, grab bars, walk-in showers, stair lifts, wider doorways, a first-floor bedroom.
- Adult day care: daytime supervision and activities that also give a family caregiver a break.
- Paying a family caregiver: compensating a son, daughter or other relative who has cut back work to help.
- Long-term care insurance premiums: keeping an existing policy in force when premiums rise.
You still have to keep paying property taxes, homeowners insurance and any HOA dues, and keep the home in reasonable repair. Falling behind on those obligations can make the loan due (CFPB). A care budget should leave room for them.
What happens if you move into a nursing home or assisted living?
If you live somewhere else, such as a nursing home, for more than 12 consecutive months, the home is no longer your principal residence and the loan can become due. That does not apply while a co-borrower or eligible non-borrowing spouse still lives in the home.
A HECM requires the home to be your principal residence, and you certify occupancy each year. A short hospital stay or a few weeks of rehab is not the issue. The rule that matters is the 12-consecutive-month limit: once you have lived elsewhere for medical reasons for more than 12 months in a row, the loan can be called due (CFPB). At that point the home is usually sold, or the family repays the balance to keep it.
Plan for the move you hope never happens
If a facility move looks likely within a few years, a reverse mortgage may cost more in upfront fees than it delivers. Upfront costs include a 2% initial mortgage insurance premium on the maximum claim amount, plus origination and closing costs, so a short loan life makes those costs expensive per year of use.
If one spouse needs facility care and the other stays home, the picture changes. When both spouses are borrowers, the loan does not become due while the other borrower still lives there. A spouse who is not on the loan may be protected as an eligible non-borrowing spouse; read our guide to the non-borrowing spouse rules before you assume either way.
Which payout option fits which care need?
Match the payout to the shape of the cost: a line of credit for irregular or rising needs, monthly tenure or term payments for steady care bills, and a lump sum mainly when paying off an existing mortgage.
Adjustable-rate HECMs offer several ways to receive money; fixed-rate HECMs pay only as a single lump sum at closing. You can usually change your payment plan later for a small fee. See payout options for the full list.
| Care need | Typical cost pattern | Payout option that often fits |
|---|---|---|
| Ramps, bathroom remodel, stair lift | One-time or a few large bills | Line of credit draw (or lump sum if also paying off a mortgage) |
| Part-time home aide | Steady monthly cost | Tenure payments, or modified tenure (monthly payments plus a line of credit) |
| Aide hours that may increase over time | Rising and unpredictable | Line of credit, drawn as needed |
| Adult day care a few days a week | Steady monthly cost | Term or tenure payments |
| Paying a family caregiver for a set period | Known amount for a known time | Term payments |
| Long-term care insurance premiums | Annual or monthly bill | Line of credit or modest tenure payments |
The unused part of a HECM line of credit grows over time at the loan’s interest rate plus the 0.5% annual mortgage insurance premium. That growth is extra borrowing capacity, not earnings and not a promise of value, but it is one reason some households open a reverse mortgage line of credit before care is needed.
Remember the first-year limit: in the first 12 months you can generally draw the greater of 60% of your principal limit or your mandatory obligations plus 10% of the principal limit. A large renovation planned for month two may need to be phased.
To see roughly how much a household your age might access, try the reverse mortgage calculator. It gives an estimate only; a licensed lender sets actual terms after counseling, appraisal and underwriting.
Will a reverse mortgage affect Medicaid or SSI?
Loan proceeds are not income and do not affect Social Security or Medicare. They can affect Medicaid and SSI if you keep the money past the month you receive it and it pushes your countable assets over the limit.
Reverse mortgage advances are loan proceeds, so they are not generally treated as taxable income (CFPB). Means-tested programs work differently. Medicaid, which pays for much long-term care for people with limited assets, and Supplemental Security Income look at what you hold. Money drawn and spent in the same month is usually not a problem; money left sitting in a bank account into the next month can count as an asset.
Draw only what you will spend
With a line of credit, unused funds stay in the loan rather than in your bank account. If Medicaid eligibility may matter now or later, talk with a benefits counselor or elder-law attorney before choosing a lump sum.
Interest on a reverse mortgage is generally not deductible until it is actually paid, usually when the loan is paid off (IRS Publication 936). Ask a tax adviser how that applies to you and your estate.
How should adult children be involved in care planning?
Invite them in early. A reverse mortgage affects what happens to the home later, and children are often the ones coordinating care, so a shared plan prevents surprises and pressure.
The decision belongs to the homeowner. Still, families tend to make better choices when they talk openly about care preferences, the likely cost of help at home, and what the home is meant to do: fund care now, pass to heirs, or some of both. The CFPB publishes a discussion guide written for exactly this conversation (CFPB discussion guide).
- Step 1
Estimate the care need
List the help needed today and what may be needed in two to five years: hours of aide time, home changes, day programs.
- Step 2
Map every resource
Savings, income, insurance, veterans or state programs, family time, and home equity. A reverse mortgage is one tool among several.
- Step 3
Agree on the home’s role
Decide together whether keeping the home for heirs matters more than using its equity for care, and write it down.
- Step 4
Attend counseling together
HUD-approved counseling is required before you apply. Adult children can usually join, and it is the best place to ask hard questions.
- Step 5
Set up safeguards
Consider who holds power of attorney, who sees statements, and how draws for care are approved and recorded.
If a family member will be paid to provide care, put the arrangement in writing with a clear rate and duties. It protects the caregiver and avoids disputes among siblings later.
When is a reverse mortgage a poor fit for long-term care?
It is usually a poor fit if a move to a facility is likely soon, if you cannot keep up with taxes and insurance, or if leaving the home to heirs is the top priority.
- Facility care is likely within a year or two, so the 12-month rule would end the loan quickly after you paid upfront costs.
- Your budget cannot cover property taxes, insurance and upkeep; the lender may require a Life Expectancy Set-Aside, which reduces the money available for care.
- You may qualify for Medicaid soon and have not received benefits advice.
- Keeping the home debt-free for children is your main goal. The balance grows over time and equity shrinks.
- The home needs major repairs to meet FHA property standards and there is little equity left after a payoff.
Alternatives worth comparing include selling and moving somewhere easier to manage, a HECM for Purchase to buy a single-level home, a HELOC or home equity loan if you can make monthly payments (comparison), and a single-purpose reverse mortgage from a state or local agency for repairs, where available. Read the full pros and cons too.
What to do next
Estimate your numbers, book HUD-approved counseling, and compare offers from more than one FHA-approved lender.
Run your figures in the reverse mortgage calculator, then find a HUD-approved counselor through HUD’s counselor search or by calling 1-800-569-4287. Counseling typically costs about $125 to $200; ask the agency about fee waivers. Learn more in our HECM counseling guide and review costs and fees before you sign anything.
About Mortgages+
Mortgages+ is a marketing and education platform, not a lender or government agency, and is not affiliated with or endorsed by HUD or FHA. Figures here are for education; actual terms come from a licensed lender.
Frequently asked questions
Can a reverse mortgage pay for in-home care?
Yes. HECM proceeds can be used for any purpose, including home care aides, adult day care, home modifications and paying a family caregiver, as long as you keep meeting the loan obligations.
Can I use a reverse mortgage to pay for a nursing home?
Not well over the long term. If you live in a nursing home or other facility for more than 12 consecutive months, the home is no longer your principal residence and the loan can become due, unless a co-borrower or eligible non-borrowing spouse still lives there.
Does reverse mortgage money affect Medicaid?
It can. Proceeds are loan advances rather than income, but money you keep past the month you receive it may count as an asset for Medicaid or SSI. Speak with a benefits counselor or elder-law attorney first.
Can I pay my daughter or son to be my caregiver with reverse mortgage funds?
Yes, the money can be used to pay a family caregiver. Put the arrangement in writing with a clear rate and duties so everyone in the family understands it.
Which payout option is best for care costs?
A line of credit suits unpredictable or rising care costs because you draw only what you need, and the unused portion grows. Tenure or term monthly payments suit steady, predictable bills.
Need funds for care quickly? Compare a home equity line pre-approval for care costs alongside a reverse mortgage.
Keep reading
 Reverse Mortgage Payout Options ExplainedHECM borrowers can take a lump sum, monthly payments for life (tenure) or a set term, a line of credit, or a mix. Fixed-rate loans pay only a lump sum at closing.
 Reverse Mortgage Line of Credit: How It GrowsA HECM line of credit lets you borrow only when needed. The unused portion grows monthly at the loan rate plus 0.5% and can’t be frozen while you meet obligations.
 Reverse Mortgage Rules for a Non-Borrowing SpouseAn eligible non-borrowing spouse can usually stay in the home after the borrower dies if HUD’s conditions are met, but cannot draw more money from the reverse mortgage.
 What Happens to a Reverse Mortgage When the Borrower Dies?When the last borrower dies, the reverse mortgage becomes due. Heirs can sell, keep the home by paying the lesser of the balance or 95% of value, or hand it back.
Sources
Content reviewed November 18, 2026 against these authoritative sources.
- 1.NCOA: Use Your Home to Stay at Home (federally approved reverse mortgage booklet)
- 2.CFPB: What is a reverse mortgage?
- 3.CFPB: Reverse mortgage key terms
- 4.CFPB: Reverse mortgage answers
- 5.CFPB: Reverse mortgages: a discussion guide (PDF)
- 6.IRS: Publication 936, Home Mortgage Interest Deduction
- 7.HUD: Find a HUD-approved HECM counselor
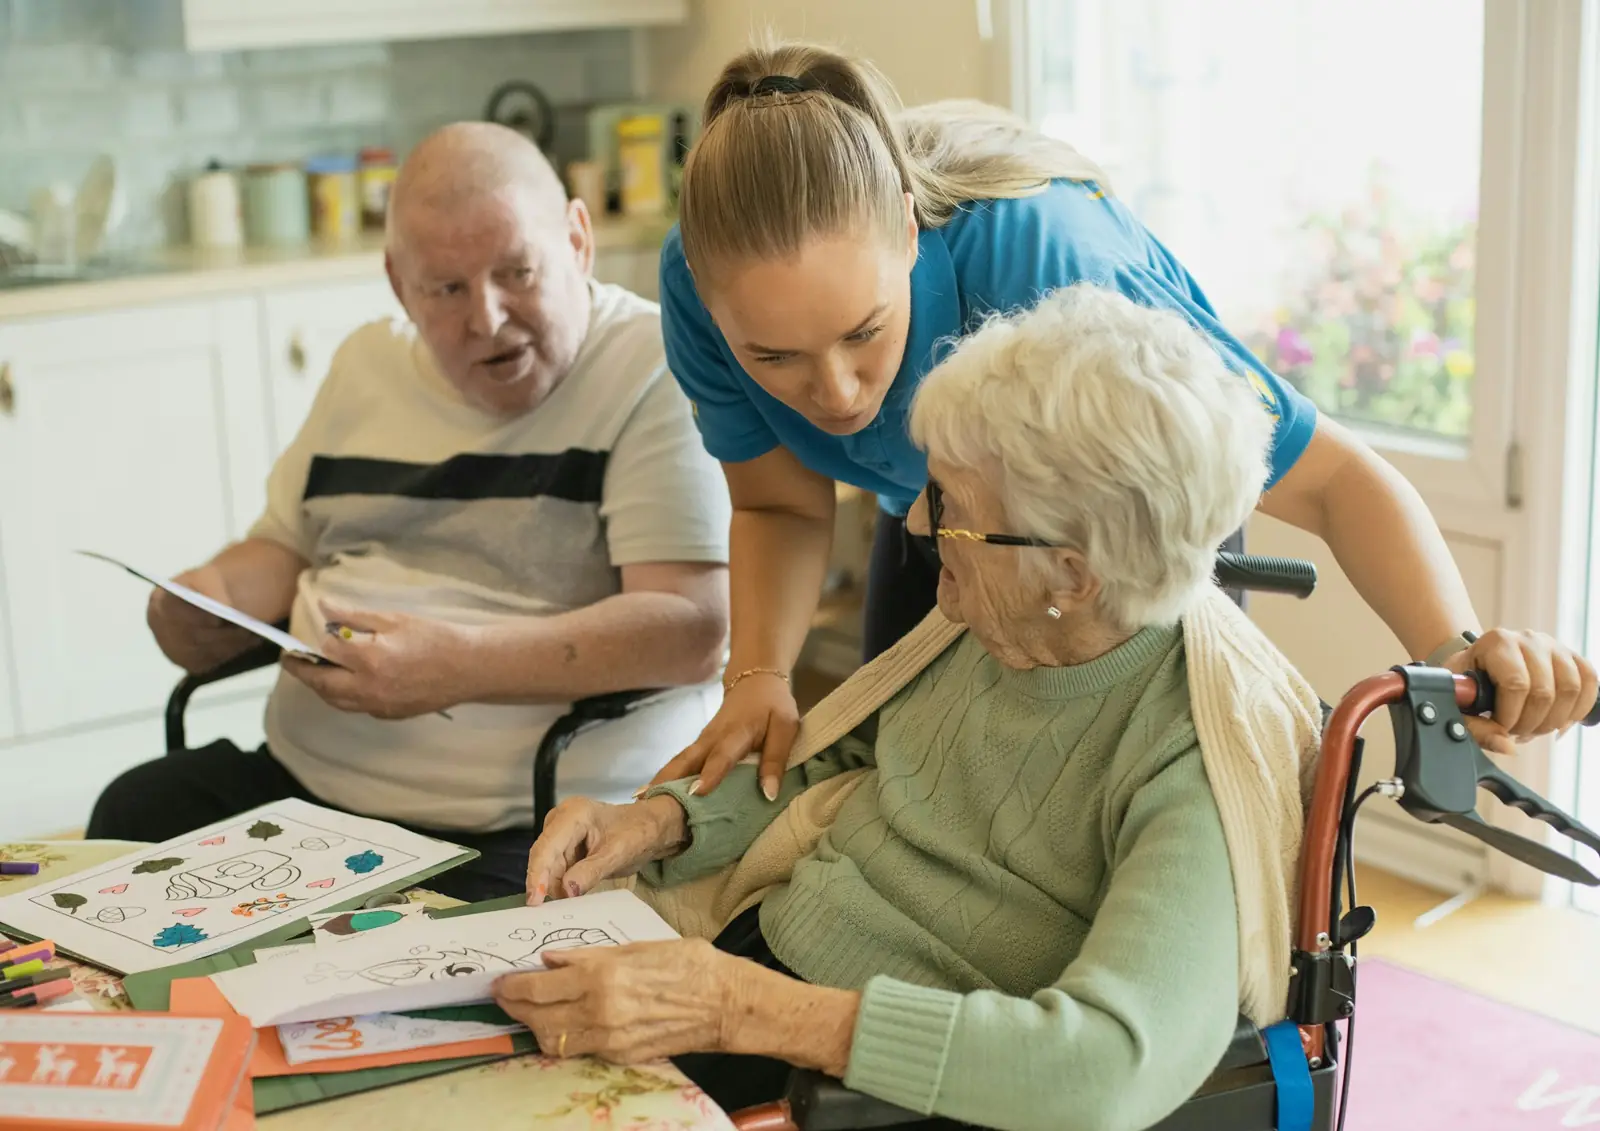
Photo: In-home caregiver spending time with an older couple in their kitchen by Age Cymru (Unsplash License).
Your next step
Put your biggest investment to work for you
Tell us a little about the home. A reverse mortgage specialist will walk you — and your family, if you like — through what you could qualify for, what it costs, and whether it’s the right fit. No pressure, no obligation.
- No monthly mortgage payment required*
- Stay in the home you love
- Non-recourse FHA-insured HECM options
- Adult children welcome on every call
*You must still pay property taxes, homeowners insurance, HOA dues and maintain the home.
Prefer to run the numbers first? Try the reverse mortgage calculator →Important disclosures
Mortgages+ is an independent marketing and education platform. We are not a lender, do not make loans, and are not affiliated with or endorsed by the U.S. Department of Housing and Urban Development (HUD), the Federal Housing Administration (FHA) or any government agency. Mortgages+ may receive compensation from some companies featured on this site. This may affect which companies appear and where. Information on this page is general education, not financial, legal or tax advice. Estimates are illustrative; actual loan amounts, rates and costs depend on the lender, the appraisal, current rates, HUD rules and underwriting. A reverse mortgage is a loan: interest and fees are added to the balance each month, the balance grows over time, and equity declines. Borrowers must live in the home as their principal residence, keep paying property taxes, homeowners insurance and HOA dues, and maintain the home, or the loan may become due and the home may be subject to foreclosure. HECM borrowers must complete counseling with an independent HUD-approved counselor. Consult a tax adviser or benefits counselor about how a reverse mortgage may affect taxes or means-tested benefits such as Medicaid or SSI.