Reverse mortgage guide · HECM counseling
HECM Counseling: What to Expect and How to Prepare
HECM counseling is a required session with an independent HUD-approved counselor before you apply. It usually costs about $125 to $200 and can be by phone or in person.
- Sourced from HUD, CFPB, FTC & NCOA
- 2026 FHA limit: $1,249,125
- No cost · No obligation · No credit check
Before anyone can apply for a HECM reverse mortgage, they must talk with a HUD-approved counselor who does not work for the lender. Many families say it is the most useful hour of the whole process. Here is what the session covers, what it costs, how to find a counselor, and how to get the most out of it.
Key takeaways
- Counseling with a HUD-approved agency is mandatory before you apply for a HECM, and the counselor must be independent of the lender.
- Sessions typically cost about $125 to $200; ask the agency about fee waivers or reductions if cost is a problem.
- You can usually meet by phone or in person, and you receive a counseling certificate the lender needs to proceed.
- Adult children and other trusted people are welcome to join, and it helps to bring a written list of questions.
- Find a counselor through HUD’s online search or by calling HUD at 1-800-569-4287.
Is counseling required for a reverse mortgage?
Yes. Every HECM borrower must complete a session with a HUD-approved HECM counselor before applying. A lender cannot take your application until you have your counseling certificate.
HUD requires counseling because a reverse mortgage is a big, long-term decision that uses the equity in your home, often your largest asset (HUD). The session is meant to make sure you understand how the loan works, what it costs, what you must keep doing to stay in good standing, and whether another option might fit you better. It is a protection for you, not a sales step.
If both spouses will be borrowers, both should attend. If one spouse is under 62 or will not be on the loan, they should still attend, because the rules for a non-borrowing spouse affect whether they can stay in the home later. Many proprietary or jumbo reverse mortgages also require counseling, depending on the lender and the state.
Who provides HECM counseling, and why must it be independent?
Counseling is provided by HUD-approved housing counseling agencies, many of them nonprofits. The counselor does not work for the lender and is not paid to sell you a loan.
Independence is the point. A loan officer is paid when a loan closes; a counselor is not. That means the counselor can tell you plainly if a reverse mortgage looks like a poor fit, and can walk you through alternatives such as selling, downsizing, a HELOC, or local programs for seniors (CFPB).
Be careful with ‘referrals’
No one should charge you an upfront fee to find a counselor, and no one should pressure you to skip or rush counseling. Those are red flags the FTC and CFPB warn about. You can pick any agency from HUD’s list yourself. Read more in our guide to avoiding scams.
What does a HECM counseling session cover?
A counselor explains how a HECM works, its costs, your payout choices, your ongoing obligations, what happens when the loan comes due, and other ways to meet your goals.
- How a reverse mortgage works and how the loan balance grows over time as interest and premiums are added.
- The costs: the 2% upfront FHA premium, the 0.5% annual premium, origination fees, closing costs and interest. See reverse mortgage costs and fees.
- Your payout choices, such as a lump sum, monthly payments or a line of credit. See payout options.
- Your obligations: living in the home, paying property taxes, homeowners insurance and HOA fees, and keeping the home in good repair.
- When the loan becomes due, and what your heirs’ choices will be.
- How the money could affect means-tested benefits such as Medicaid or SSI.
- Alternatives, including selling, downsizing, other loans, and local assistance programs.
- Your own budget, so you can see whether you can keep up with taxes and insurance for the long run.
The counselor will often run sample numbers for your age and home value. It helps to try the reverse mortgage calculator beforehand so you arrive with a rough range in mind and can ask sharper questions.
How much does HECM counseling cost?
Counseling typically costs about $125 to $200. If you cannot afford it, ask the agency about a fee waiver or reduction before your session.
| Question | Answer |
|---|---|
| Required? | Yes, before applying for a HECM |
| Who provides it | HUD-approved housing counseling agencies, independent of lenders |
| Typical cost | About $125 to $200 |
| Fee help | Waivers or reductions may be available; ask the agency |
| Format | By phone or in person, depending on the agency |
| Who can attend | Borrowers, spouses, and family members or advisers you invite |
| What you receive | A counseling certificate your lender needs to take your application |
| How to find one | HUD’s online counselor search or 1-800-569-4287 |
In many cases the fee can be paid from loan proceeds at closing, but agencies often ask for it up front. Either way, the cost is small next to the size of the decision. NCOA’s federally approved booklet is free and covers the same ground if you want to read ahead (NCOA).
How do I find a HUD-approved HECM counselor?
Use HUD’s HECM counselor search, its housing counseling locator, or call HUD at 1-800-569-4287 to get a list of approved agencies near you.
HUD keeps a searchable list of approved HECM counseling agencies by state (HUD HECM counselor list) and a general housing counseling locator (HUD housing counseling). You can also call HUD at 1-800-569-4287. Choose any approved agency you like; a lender may give you a list, but you are not required to use a particular one.
How to prepare for your counseling session
Gather your home and income details, invite the people you trust, write down your questions, and ask the counselor to run numbers for your exact situation.
- Step 1
Pick an agency
Choose a HUD-approved agency from HUD’s list or by phone, and ask about the fee and any waiver.
- Step 2
Choose phone or in person
Pick the format you are most comfortable with. In-person can help if hearing or reading small print is hard.
- Step 3
Gather your paperwork
Bring a recent mortgage statement if you have one, your property tax bill, homeowners insurance, HOA dues, and a simple list of monthly income and expenses.
- Step 4
Invite family or a trusted adviser
Adult children, a financial planner or an elder-law attorney can listen, take notes and ask follow-up questions.
- Step 5
Write your questions
Use the list below, plus anything specific to your health, your spouse or your plans for the home.
- Step 6
Get your certificate
After the session, the agency issues a counseling certificate. Keep a copy and give one to the lender you choose.
Why adult children should come
A reverse mortgage affects what happens to the house later. When children hear the rules from a neutral counselor, including their choices after the last borrower dies, there are fewer surprises and fewer family disagreements. See what happens when you die.
What questions should I ask a HECM counselor?
Ask how much you could receive after costs, what could make the loan come due, how it affects your spouse and heirs, and whether a different option would serve you better.
- Roughly how much could I receive after all costs and any mortgage payoff?
- Which payout option fits my goal: a lump sum, monthly payments or a line of credit?
- What happens if I go into a care facility for more than 12 consecutive months?
- What happens to my spouse if they are younger than 62 or not on the title?
- Can I afford my property taxes, insurance and upkeep for the long run? Could the lender require a set-aside?
- How would this affect my Medicaid or SSI eligibility, if I receive them now or might later?
- What will my children’s options be when the loan comes due?
- Are there cheaper ways to meet my goal, such as a single-purpose loan or a local program?
The CFPB’s discussion guide is designed for exactly this conversation and is worth printing (CFPB). After counseling, compare at least two lender quotes, run the reverse mortgage calculator again, and review our main guide to reverse mortgages if anything is still unclear.
Mortgages+ is an education and marketing platform, not a lender or counseling agency, and is not affiliated with HUD or FHA.
Frequently asked questions
Is HECM counseling mandatory?
Yes. You must complete counseling with a HUD-approved HECM counselor before you can apply for a HECM reverse mortgage.
How much does reverse mortgage counseling cost?
It typically costs about $125 to $200. Ask the counseling agency about fee waivers or reductions if the cost is a hardship.
Can I do HECM counseling over the phone?
Yes. Many HUD-approved agencies offer counseling by phone as well as in person. Ask the agency which formats it offers.
Can my children attend my reverse mortgage counseling?
Yes. You can invite adult children or another trusted person, and it is often a good idea so they understand the loan and their options later.
Can the lender choose my counselor?
No. You choose any HUD-approved agency yourself. Counselors are independent of lenders, and you should be wary of anyone charging a fee to refer you to counseling.
Your counselor may ask you to compare alternatives — a quick refinance or equity pre-approval gives you real numbers to bring.
Keep reading
 Reverse Mortgage Costs and Fees, ExplainedHECM costs include a 2% upfront FHA premium, a 0.5% annual premium, an origination fee capped at $6,000, closing costs and interest, mostly paid from loan proceeds.
 Reverse Mortgage Eligibility RequirementsTo qualify for a HECM reverse mortgage, the youngest borrower must be 62+, live in the home, have sizable equity, be current on federal debt and complete counseling.
 How to Avoid Reverse Mortgage ScamsWatch for pressure to buy annuities, contractors pushing loans, deed sign-overs and rushed counseling. Verify the lender, use your right to cancel, and report fraud.
 Reverse Mortgage Rules for a Non-Borrowing SpouseAn eligible non-borrowing spouse can usually stay in the home after the borrower dies if HUD’s conditions are met, but cannot draw more money from the reverse mortgage.
Sources
Content reviewed November 18, 2026 against these authoritative sources.
- 1.HUD: Find a HUD-approved HECM counselor
- 2.HUD: Housing counseling (find a counselor)
- 3.HUD: HECM program (Home Equity Conversion Mortgages for Seniors)
- 4.CFPB: Reverse mortgage answers
- 5.CFPB: Reverse mortgages: a discussion guide (PDF)
- 6.NCOA: Use Your Home to Stay at Home (federally approved reverse mortgage booklet)
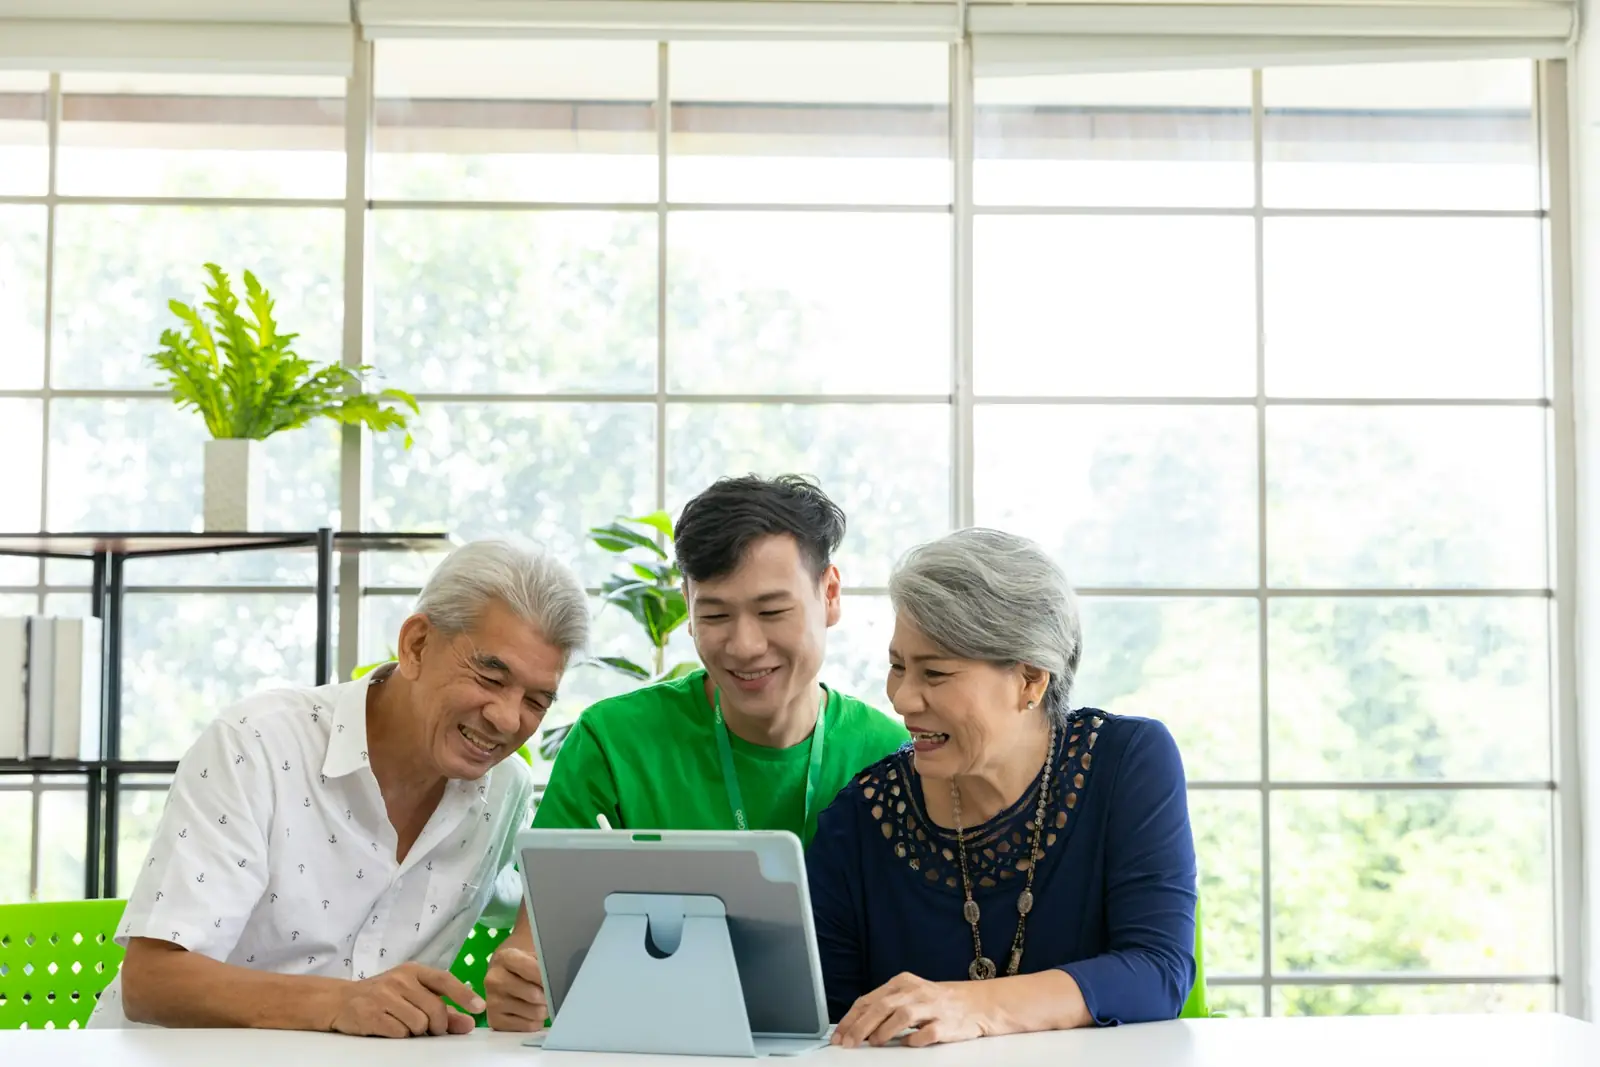
Photo: Adult son helping his parents compare options on a tablet by Grab (Unsplash License).
Your next step
Put your biggest investment to work for you
Tell us a little about the home. A reverse mortgage specialist will walk you — and your family, if you like — through what you could qualify for, what it costs, and whether it’s the right fit. No pressure, no obligation.
- No monthly mortgage payment required*
- Stay in the home you love
- Non-recourse FHA-insured HECM options
- Adult children welcome on every call
*You must still pay property taxes, homeowners insurance, HOA dues and maintain the home.
Prefer to run the numbers first? Try the reverse mortgage calculator →Important disclosures
Mortgages+ is an independent marketing and education platform. We are not a lender, do not make loans, and are not affiliated with or endorsed by the U.S. Department of Housing and Urban Development (HUD), the Federal Housing Administration (FHA) or any government agency. Mortgages+ may receive compensation from some companies featured on this site. This may affect which companies appear and where. Information on this page is general education, not financial, legal or tax advice. Estimates are illustrative; actual loan amounts, rates and costs depend on the lender, the appraisal, current rates, HUD rules and underwriting. A reverse mortgage is a loan: interest and fees are added to the balance each month, the balance grows over time, and equity declines. Borrowers must live in the home as their principal residence, keep paying property taxes, homeowners insurance and HOA dues, and maintain the home, or the loan may become due and the home may be subject to foreclosure. HECM borrowers must complete counseling with an independent HUD-approved counselor. Consult a tax adviser or benefits counselor about how a reverse mortgage may affect taxes or means-tested benefits such as Medicaid or SSI.