Homeowner guide · Home warranty
Is a Home Warranty Worth It? How to Decide for Your Home
A home warranty can be worth it if your systems and appliances are older and a surprise repair would strain your budget; read the service fee, caps and exclusions first.
A home warranty is a service contract that pays for repair or replacement of covered systems and appliances when they fail from normal wear. It is not insurance, and it is not the builder's warranty. Whether it pays off depends on the age of what is in your home, your savings and the fine print. Here is how to decide.
Key takeaways
- A home warranty is a service contract: you pay a yearly price plus a service fee each time a technician comes out.
- Value depends mostly on the age of your HVAC, water heater and appliances, and on per-item coverage caps.
- Common exclusions include pre-existing conditions, code upgrades, improper maintenance and some components.
- It does not replace homeowners insurance, which covers sudden damage like fire, storms and theft.
- A seller-paid plan at closing costs you nothing up front, but read the terms before you rely on it.
What is a home warranty, exactly?
A home warranty is a one-year service contract that covers repair or replacement of listed home systems and appliances that break down from normal wear and tear, in exchange for an annual price plus a fee per service call.
The FTC calls home warranties what they legally are: service contracts that cost extra and typically cover repairs or replacement of appliances and systems such as air conditioning (FTC). Federal rules distinguish them from a manufacturer's written warranty (16 CFR Part 700), and each state decides how home warranty companies are licensed and supervised. In Texas, for example, they are licensed as residential service companies by the Texas Real Estate Commission (TREC).
| Coverage | What it pays for | Who provides it |
|---|---|---|
| Home warranty (service contract) | Repair or replacement of covered systems and appliances that fail from normal wear | A home warranty company |
| Homeowners insurance | Sudden, accidental damage: fire, wind, hail, theft, liability | An insurer, usually required by your lender |
| Builder warranty | Workmanship and defects in a newly built home, for set periods | The builder or its warranty provider |
| Manufacturer warranty | Defects in a specific appliance, usually for a short period | The appliance maker |
If you are comparing a warranty with your insurance policy, our guide to choosing homeowners insurance before closing explains what insurance covers that a warranty never will.
When is a home warranty worth it?
It is most likely worth it when several major systems or appliances are near the end of their typical life, when a $3,000 to $8,000 surprise repair would push you into debt, and when the plan's caps cover the items you are worried about.
- Your inspection shows an older furnace, AC or heat pump, water heater and kitchen appliances.
- You have just spent your savings on the down payment and closing costs.
- You are not handy and do not have a trusted repair company yet.
- The seller is offering to pay for the first year at closing.
- The plan's per-item caps are high enough to cover a real replacement of your oldest system.
It is less likely to pay off when the home is new or recently renovated, when you have a healthy emergency fund, or when the caps and exclusions mean the costly failures you fear would not be covered anyway. The repair amounts above are illustrative; get local quotes before you decide.
The emergency-fund alternative
Some owners skip the warranty and deposit the same money each month into a home repair fund. After a few years without major failures, that fund can exceed what the plan would have paid out. The tradeoff: no protection against an expensive failure in year one.
Free · no obligation · Home warranty
Get matched with home warranty pros near you
Secure & privateNo costNo obligationConsent on the next screen
How do you check the age of what you are covering?
Use your inspection report and the data plates on each unit, then compare the ages with typical lifespans. Systems already past their typical life are where a warranty can help most, if the plan does not exclude them.
| System or appliance | Typical life (years) |
|---|---|
| Conventional water heater (gas or electric) | 6 to 12 |
| Tankless water heater | About 10 (often longer with maintenance) |
| Central air conditioner | 7 to 15 |
| Heat pump | 10 to 15 |
| Furnace | 15 to 25 |
| Dishwasher | About 9 |
| Refrigerator | 9 to 13 |
| Clothes dryer | About 13 |
Figures come from InterNACHI's life-expectancy chart (InterNACHI). If you have not closed yet, our buyer's inspection walkthrough shows how to get system ages written into the report.
What does a home warranty usually not cover?
Most plans exclude pre-existing conditions, damage from poor maintenance, code upgrades, permits, cosmetic parts and items not listed in the contract, and most cap what they pay per system or per year.
- Pre-existing conditions: problems that existed before coverage began, which can be disputed if the inspection noted wear.
- Maintenance failures: a furnace that was never serviced, a water heater never flushed.
- Code upgrades and permits: when replacement requires new venting, refrigerant or electrical work to meet code.
- Per-item caps: a cap on HVAC or a water heater that is lower than a full replacement.
- Waiting periods: many plans do not cover claims made in the first days or weeks unless bought at closing.
- Optional coverage: pools, septic, well pumps and second refrigerators often cost extra.
The FTC tells consumers to compare the upfront price with hidden costs such as service fees, to check caps and exclusions, and to research a company's claims reputation, because a plan is only as good as the company behind it (FTC).
How do you compare home warranty quotes?
Compare the annual price, the service-call fee, the per-item caps on your oldest systems, the exclusions, the waiting period, how contractors are assigned and how claims are handled. Get it all in writing.
| Question | Plan A | Plan B |
|---|---|---|
| Annual price | ||
| Service fee per visit | ||
| Cap on HVAC repair or replacement | ||
| Cap on water heater | ||
| Waiting period before coverage | ||
| Pre-existing condition rule | ||
| Can I choose my own contractor? | ||
| Cancellation terms and refund |
A worked example, illustrative only: a plan costs $600 a year with a $100 service fee. If you have two covered repairs in a year, you pay $800 in total. If one of them is a $4,500 AC replacement that the plan covers in full, you are well ahead. If the plan caps AC at $1,500, your saving is much smaller. Caps decide the math more than the headline price.
How do you get the most from a home warranty once you have one?
Keep your inspection report and maintenance receipts, file claims as soon as something fails, ask for the cap and the contractor's diagnosis in writing, and escalate in writing if a claim is denied.
- Step 1
Document the starting point
Save the inspection report, photos of each unit's data plate and the contract in one folder on day one.
- Step 2
Maintain what is covered
Service the furnace and AC yearly and flush the water heater as the maker recommends. Keep the receipts; denied claims often cite missing maintenance.
- Step 3
File promptly
Call or file online as soon as something fails. Do not hire your own contractor first unless the contract allows it, or you may not be reimbursed.
- Step 4
Get decisions in writing
Ask for the technician's diagnosis, the coverage decision and the cap applied, by email.
- Step 5
Escalate if needed
Appeal denials in writing. If that fails, contact your state regulator and report problems to the FTC at ReportFraud.ftc.gov.
Should you get a home warranty at closing?
If the seller will pay for a first-year plan, accept it and read the contract. If you are paying yourself, there is no rush: you can buy a plan after closing, though a waiting period may apply.
A plan paid at closing appears on your Closing Disclosure, which you receive at least three business days before closing (CFPB). Check that the plan, price and who is paying match what you agreed. Your agent may suggest a specific company. That is fine, but you may choose another. If cash is tight after closing, run your numbers with the closing cost estimator and the monthly payment calculator before adding another bill.
Request a match below and a participating warranty company serving your ZIP will contact you with written terms. Compare its plan with others using the worksheet above. Planning the rest of your first year? Our moving checklist for new owners covers utilities, address changes and move-in tasks.
Frequently asked questions
Is a home warranty the same as homeowners insurance?
No. Insurance covers sudden damage such as fire, storms and theft. A warranty covers breakdowns from normal wear of listed systems and appliances.
How much does a home warranty cost?
You pay an annual price plus a service fee for each repair visit. Prices vary by company, state, home size and coverage options, so compare written quotes.
Can I buy a home warranty after closing?
Yes. Most companies sell plans to current owners at any time, though coverage may start after a waiting period.
Will a home warranty cover a system that is already old?
Usually yes, if it is working when coverage begins and was maintained. Problems that existed before coverage started are typically excluded.
Can I cancel a home warranty?
Most contracts allow cancellation, sometimes with a fee or a prorated refund. State rules differ, so read the cancellation section before you buy.
Who regulates home warranty companies?
States do. Depending on the state, it may be the insurance department, a real estate commission (as in Texas) or another agency.
Still shopping for the house itself? A pre-approval that includes room for repairs helps you pick a home your budget can maintain.
Related on Mortgages+
More homeowner guides
 Home Security for New Homeowners: Your Move-In ChecklistNew homeowners should rekey exterior locks, reset every code and smart device, test smoke and CO alarms, then choose monitoring and ask the insurer about discounts.
 Water Filtration for a New Home: Test First, Then TreatTest before you filter. On city water, read the utility’s annual water report; on a well, get a certified-lab test. Then buy NSF-certified gear that fits the results.
 Moving Checklist for Home Buyers: Week by Week to ClosingBook movers 4–8 weeks before closing, verify an interstate mover’s USDOT number, get written estimates after a survey, and plan move day around funding and keys.
 Paying for Solar Panels With a HELOC: Options ComparedA HELOC can fund solar at the cash price with no dealer fee, but your home secures it and the rate can change. Compare it with cash, solar loans, leases and PPAs first.
Run a home warranty business? Bid on home warranty leads from homeowners like these in the Mortgages+ partner marketplace.
Sources
Content reviewed November 18, 2026 against these authoritative sources.
- 1.FTC: So, what's the deal with home warranties?
- 2.eCFR: 16 CFR Part 700: Magnuson-Moss Warranty Act interpretations
- 3.InterNACHI: Standard Estimated Life Expectancy Chart for Homes
- 4.Texas Real Estate Commission: Residential Service Companies (Home Warranties)
- 5.CFPB: What is a Closing Disclosure?
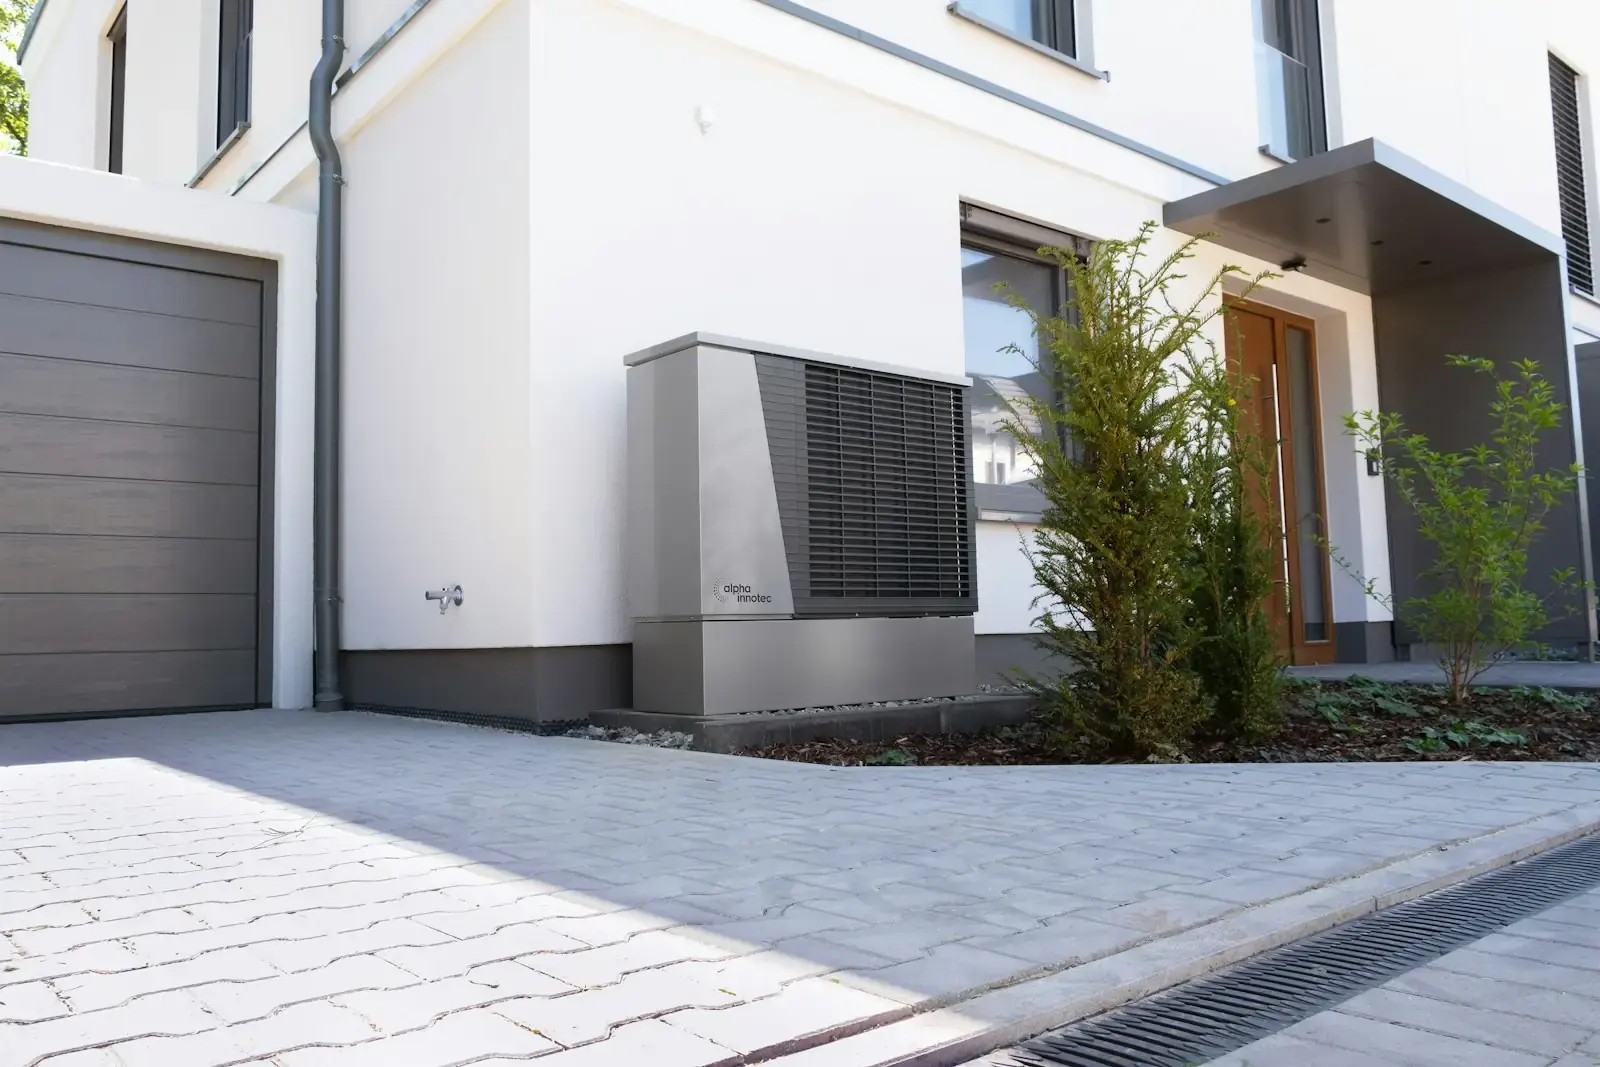
Photo: A modern house with a heat pump unit by alpha innotec on Unsplash (Unsplash License).
Mortgages+ is a marketing platform, not a lender, insurer or service provider. When you request help, we match your request with one participating home warranty provider serving your ZIP code, who pays Mortgages+ for it. Mortgages+ may receive compensation from some companies featured on this site.
Ready when you are
Tell us a little about your home and we’ll match you with vetted help nearby.
Get matched →