Homeowner guide · Home equity & HELOC
What Is a HELOC? How a Home Equity Line of Credit Works
A HELOC is a revolving credit line secured by your home. You borrow as needed during a draw period, often 10 years, then repay principal and interest over a set term.
A home equity line of credit lets you use the value you have built in your home without refinancing your first mortgage. It can be the lowest-cost way to fund a renovation or replace high-rate debt, and it can also put your home at risk if you borrow more than you can repay. This guide explains how a HELOC works, how much you might qualify for, what it costs, and how it compares with a home equity loan and a cash-out refinance.
Key takeaways
- A HELOC is secured by your home: miss payments and you can lose it.
- Most lenders cap the first mortgage plus the line at about 80% to 90% of your home’s value.
- Rates are usually variable, tied to an index such as the prime rate plus a margin, with a lifetime cap.
- You have three business days after closing to cancel a HELOC on your main home.
- Interest is generally tax-deductible only when the money buys, builds or substantially improves that home.
How does a home equity line of credit work?
A lender approves a credit limit based on your equity, credit and income. During the draw period you borrow, repay and borrow again, often paying interest only. In the repayment period you can no longer draw and pay down principal and interest.
Think of a HELOC as a credit card backed by your house, with a much lower rate and much higher stakes. The CFPB describes it as a line of credit that lets you borrow against your available equity up to a limit, with your home as collateral (CFPB). You draw by transfer, check or card, and you pay interest only on what you have used.
| Phase | Typical length | What you can do | What you pay |
|---|---|---|---|
| Draw period | Often 10 years | Borrow up to your limit, repay and borrow again | Often interest only, sometimes interest plus a little principal |
| Repayment period | Often 10 to 20 years | No new draws | Principal and interest, so payments usually rise |
Plan for the payment jump
Illustrative: an interest-only payment on a $50,000 balance at 8% is about $333 a month. Repaid over 20 years at the same rate, the payment is about $418. If rates rise, both numbers rise. Some plans also end with a balloon payment, so ask.
How much can you borrow with a HELOC?
Most lenders limit your combined loan-to-value (first mortgage plus the new line) to roughly 80% to 90% of your home’s value. Your credit, income and debt-to-income ratio then decide how much of that you are approved for.
- Step 1
Estimate value
Example home value: $450,000.
- Step 2
Apply the CLTV limit
At an 85% limit: $450,000 × 0.85 = $382,500.
- Step 3
Subtract what you owe
First mortgage balance $250,000: $382,500 − $250,000 = $132,500.
- Step 4
Check affordability
That $132,500 is a ceiling. The lender will test your payments against your income before setting the line.
To see how a new payment changes your ratio, run the debt-to-income ratio calculator. Lenders typically want a credit score in the mid-600s or higher, stable income and a debt-to-income ratio in the low 40s or below, though standards differ by lender.
Free · about two minutes
See what you can borrow before you choose
One short form and a single text. Then compare lenders with real numbers.
Start my pre-approval →HELOC vs home equity loan vs cash-out refinance: which fits?
Choose a HELOC for costs that arrive over time, a home equity loan for one known amount at a fixed rate, and a cash-out refinance only if the new first-mortgage rate is close to or below what you pay now.
| HELOC | Home equity loan | Cash-out refinance | |
|---|---|---|---|
| How you get money | Draw as needed up to a limit | One lump sum | One lump sum, replaces your mortgage |
| Rate | Usually variable | Usually fixed | Fixed or adjustable |
| Your first mortgage | Stays as is | Stays as is | Paid off and replaced |
| Closing costs | Often low; some lenders waive them with conditions | Typically 2% to 5% of the loan | Typically 2% to 6% of the new loan |
| Disclosures | HELOC disclosures and CFPB booklet | Loan Estimate and Closing Disclosure | Loan Estimate and Closing Disclosure |
| Best for | Renovations in stages, ongoing costs, a backup fund | A single project or debt payoff | When a lower or similar first-mortgage rate is available |
A home equity loan is a second mortgage with fixed payments (CFPB). A cash-out refinance swaps your mortgage for a bigger one and gives you the difference (CFPB). If you locked a low first-mortgage rate, refinancing all of it to reach a smaller amount of cash usually costs more over time; test it with the refinance break-even calculator. Homeowners 62 and older have a fourth option, explained in our side-by-side of reverse mortgages, HELOCs and equity loans.
What does a HELOC cost?
Interest on what you draw, plus possible appraisal, origination, title and recording fees at opening, and sometimes an annual fee, inactivity fee or early-closure fee. Ask for every fee in writing before you apply.
- Interest: usually an index such as the prime rate plus a margin set for your file. Federal rules require the index to be outside the lender’s control and a lifetime maximum rate to be stated.
- Opening costs: appraisal or automated valuation, title search, recording fees and sometimes origination or points. Your lender may order a lender’s title policy; see our title insurance guide for homeowners.
- Ongoing fees: annual or participation fees, and occasionally fees for inactivity or each draw.
- Early-closure fee: “no closing cost” lines often recapture waived costs if you close the line within two or three years.
- Insurance: the lender will require homeowners insurance naming it as a lienholder; this is a good moment to check your homeowners coverage and lender requirements.
The lender must give you HELOC disclosures and the CFPB’s home equity booklet when you apply, and if a term in the disclosures changes before you open the account, you can walk away and get your fees back (eCFR 1026.40; CFPB booklet).
What are the risks of a HELOC, and what protects you?
The biggest risks are losing your home if you cannot pay, rising variable rates, and a line being frozen when values fall. Federal law gives you a three-day right to cancel and limits when a lender can change your terms.
- Right of rescission: you can cancel a HELOC on your principal home within three business days of opening it, under 12 CFR 1026.15.
- Frozen or reduced lines: a lender may suspend draws or cut the limit if your home’s value declines significantly or your finances materially change (CFPB). Do not count on an unused line as an emergency fund you cannot live without.
- Termination limits: a lender can demand full repayment only in narrow cases, such as fraud, failing to pay, or actions that damage the home’s value as collateral.
- Tax rules: under IRS Publication 936, interest is generally deductible only when the borrowed money buys, builds or substantially improves the home securing it. Using a line to pay credit cards does not qualify (IRS).
- Scam warning: be wary of anyone who pressures you to borrow against your home, asks for upfront fees before approval, or tells you to misstate income.
How do you apply for a HELOC?
Check your equity and credit, gather documents, compare at least three lenders on margin, fees and caps, then apply. Expect a valuation, a title search and a closing, usually within two to six weeks.
- Step 1
Know your numbers
Estimate value and first-mortgage balance, and check your credit reports for errors.
- Step 2
Gather documents
ID, pay stubs or two years of tax returns if self-employed, your mortgage statement and your insurance declarations page.
- Step 3
Compare offers
Line up the margin, the introductory rate and when it ends, the lifetime cap, all fees, the draw and repayment periods, and any early-closure fee.
- Step 4
Apply and close
Read the HELOC disclosures, attend closing, and use your three-day rescission window if anything feels wrong.
- What index and margin set my rate, and how often can it change?
- Is there a minimum draw at closing or a minimum balance I must keep?
- Can I lock part of my balance at a fixed rate, and what does that cost?
- What happens at the end of the draw period: full amortization, a balloon or a renewal option?
- What fees apply if I close the line in the first three years?
Mortgages+ is not a lender. If you want help comparing, request a match and we will connect you with licensed lenders in your ZIP code after you confirm your phone by text. Lenders on the platform are described on our page for HELOC lending partners.
Frequently asked questions
Is a HELOC a second mortgage?
Usually, yes. A HELOC is typically a second lien behind your first mortgage, though it can be a first lien on a home with no mortgage.
Can my HELOC rate go up?
Most HELOC rates are variable and move with an index such as the prime rate. Your agreement must state the maximum rate that can ever apply.
How long does it take to get a HELOC?
Often two to six weeks, depending on the valuation, title work and how quickly you provide documents.
Can I cancel a HELOC after signing?
Yes. On your principal home you generally have three business days after opening to rescind under federal law.
Is HELOC interest tax-deductible?
Generally only when the money buys, builds or substantially improves the home securing the line, under IRS Publication 936. Ask a tax adviser about your situation.
Does Mortgages+ lend money?
No. Mortgages+ is a marketplace that connects homeowners with licensed lenders after they request help and confirm their phone.
Curious what a lender would actually offer you? see how much of your home equity you can borrow with one short request and a single text.
Related on Mortgages+
More homeowner guides
 Title Insurance Explained: Owner’s vs. Lender’s PolicyTitle insurance covers ownership problems from before you bought, like forged deeds or old liens. Lenders require a lender’s policy; an owner’s policy protects you.
 Homeowners Insurance When Buying a Home: A Closing GuideYour lender needs proof of homeowners insurance before closing. Shop once your offer is accepted, insure the rebuild cost, check flood risk and send the binder early.
 How to Choose a Real Estate Agent After the 2024 Rule ChangesInterview two or three local agents, check licenses and recent sales, and compare written agreements. Since 2024, buyers sign one before touring; fees are negotiable.
 Buying a New Construction Home: Costs, Contracts and LoansTo buy new construction, get pre-approved, bring your own agent, budget for upgrades and lot premiums, compare builder incentives with other lenders, and inspect twice.
Run a home equity & heloc business? Bid on HELOC and home equity leads from homeowners like these in the Mortgages+ partner marketplace.
Sources
Content reviewed November 18, 2026 against these authoritative sources.
- 1.CFPB: What is a home equity line of credit (HELOC)?
- 2.CFPB: What you should know about home equity lines of credit (booklet)
- 3.CFPB: Can my HELOC lender freeze or reduce my line of credit?
- 4.CFPB: What is a home equity loan?
- 5.CFPB: What is a cash-out refinance?
- 6.eCFR: 12 CFR 1026.15, right of rescission
- 7.IRS: Publication 936, Home Mortgage Interest Deduction
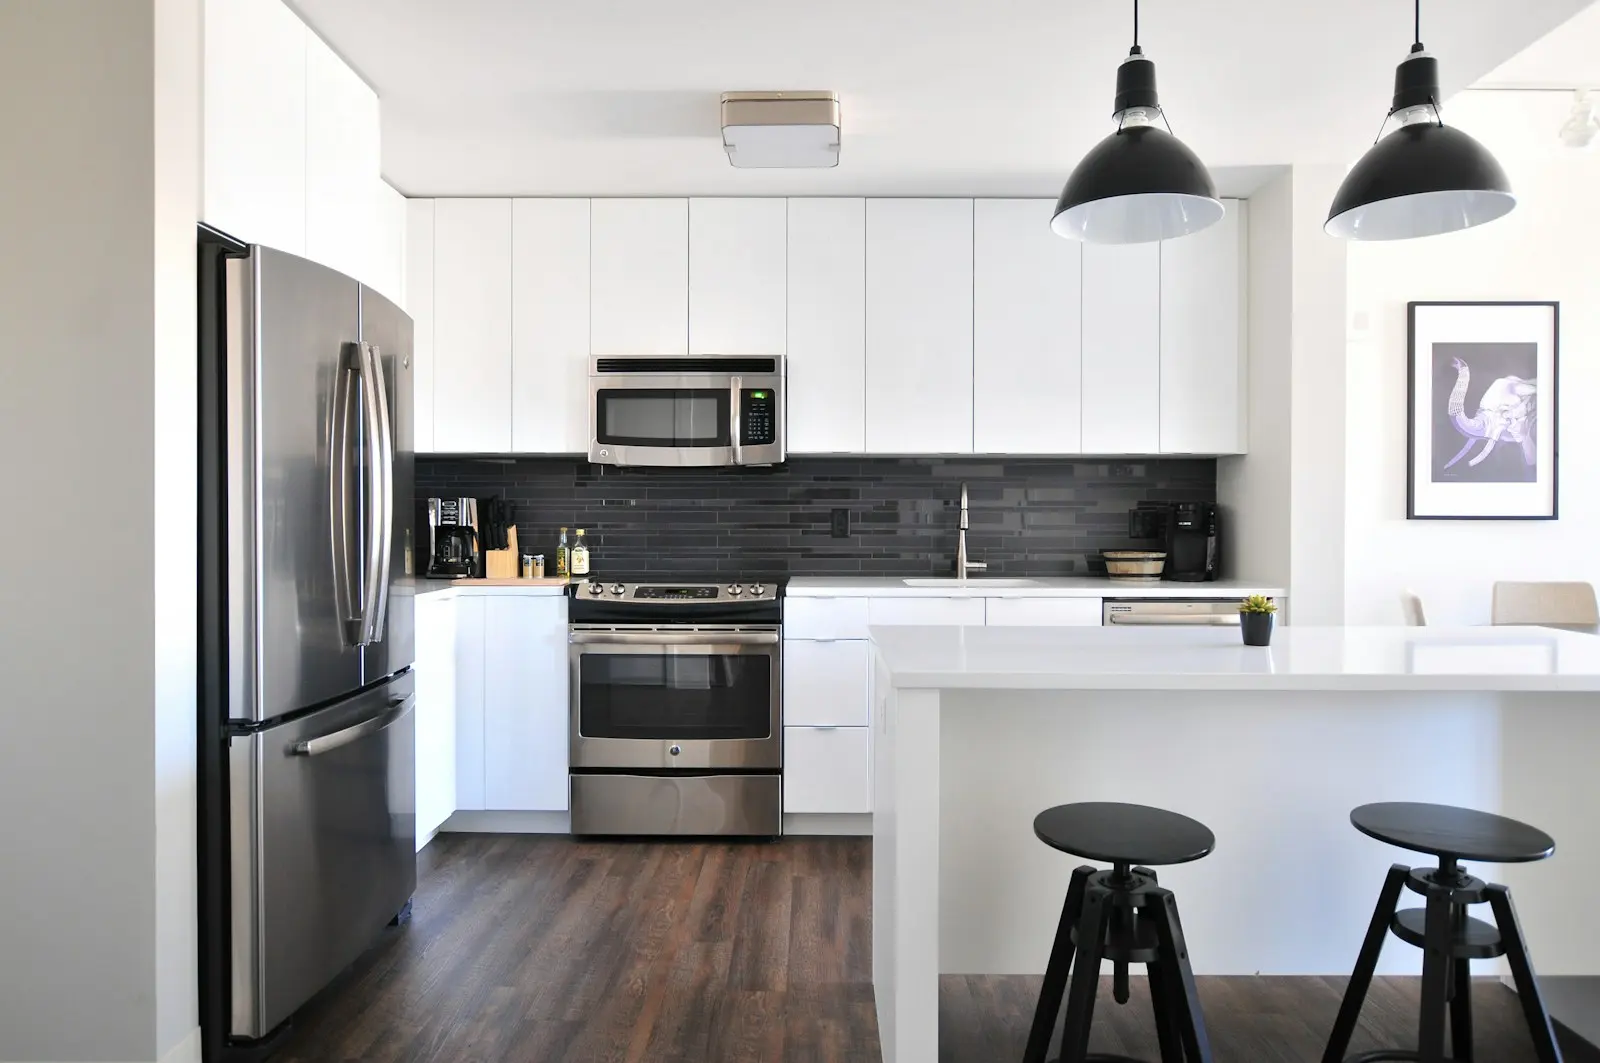
Photo: A bright, newly renovated kitchen on Unsplash (Unsplash License).
Mortgages+ is a marketing platform, not a lender, insurer or service provider. When you request help, we match your request with one participating home equity & heloc provider serving your ZIP code, who pays Mortgages+ for it. Mortgages+ may receive compensation from some companies featured on this site.
Ready when you are
Tell us a little about your home and we’ll match you with vetted help nearby.
Start my pre-approval →