For senior living communities and in-home care agencies
Senior Care Leads From Families Tapping Home Equity
Mortgages+ sends senior living communities and home care agencies consented, ZIP-targeted leads from families using a home sale, HELOC or reverse mortgage for care.
For most older Americans the house is the largest asset they own, and it is usually the account that ends up paying for care. That is why the decision to move into assisted living or to bring in a caregiver so often starts as a housing and mortgage question: sell, rent, borrow or stay. Mortgages+ meets families at that exact moment and hands the conversation to licensed providers who can help.
Key takeaways
- Care decisions and home-equity decisions happen in the same few weeks, often triggered by a fall, a hospital stay or a spouse who can no longer manage alone.
- Every lead is a verified mobile number with timestamped TCPA consent, the type of care requested, the ZIP code and the family's timeline.
- Bids start at $25 per lead from a prepaid balance, with daily caps and ZIP or state targeting you control.
- Families on a home-equity path are often private-pay for months or years before any public benefit applies, which is the window most communities and agencies plan around.
- Compliance here means state licensing, elder-financial-abuse safeguards, careful health-data handling and, for providers that bill Medicare or Medicaid, the federal Anti-Kickback Statute.
When do senior living & in-home care leads happen around a mortgage?
Every lead on Mortgages+ starts at a mortgage moment: a purchase, a refinance or an equity decision. These are the windows when homeowners need you most.
- 1
Hospital or rehab discharge
Days 0 to 21
A safe place or a caregiver now, and a way to fund the first month before the house is dealt with.
- 2
Decision to sell the family home
60 to 120 days before move-in
A community that will hold a unit or an agency that can cover the gap until closing.
- 3
Reverse mortgage counseling and closing
30 to 60 days
Hourly in-home care priced against a monthly line-of-credit draw.
- 4
HELOC or bridge loan to move first
2 to 6 weeks
A fast move-in date and a clear first-quarter cost to size the loan.
- 5
Spouse passes or can no longer caregive
Months 0 to 6
Respite, then a longer plan funded by the house the survivor now owns alone.
Why do mortgage-moment leads matter to senior living and home care?
Because the house usually pays for care. Families researching how to unlock equity through a sale, a HELOC or a reverse mortgage are, in the same breath, deciding where and how a parent will receive care and how to fund the first year of it.
Care is expensive and mostly private-pay. The Genworth and CareScout Cost of Care Survey for 2024 put the national median for a private one-bedroom in assisted living at $70,800 a year and a full-time home health aide at $77,792 a year (Genworth and CareScout 2024 survey release). Medicare generally does not pay for long-term custodial care, the help with bathing, dressing and eating that most residents need (Medicare on long-term care coverage). Savings run out quickly at those numbers, so families turn to the house.
That turn creates a predictable sequence. Someone searches how to use the equity, lands on a guide like our consumer page on paying for senior living with home equity, runs the numbers on a sale versus a loan, and asks for matched help. At that moment they have a type of care in mind, a ZIP code where the parent will live and a timeline. That is the lead you receive.
- Assisted living and memory care communities: families comparing a move-in date with a listing date or a loan closing.
- Independent living and continuing care retirement communities: downsizers who need the sale proceeds for an entrance fee or the first months of rent.
- In-home care agencies: families choosing to age in place, often using a HELOC or a reverse mortgage line of credit to fund hourly care.
- Adult day programs and respite providers: caregivers stretching budgets while the home question gets settled.
When do families make care decisions around a home sale or loan?
Most decisions cluster in four windows: right after a health event, while the house is being prepared for sale, between a reverse mortgage counseling session and closing, and when an adult child inherits a caregiving role and a property at the same time.
The timing table on this page shows each moment and what the family needs from you. The practical lesson is that care providers who wait for the house to sell arrive too late. The family has usually toured two or three communities, or interviewed agencies, before a listing agent is even hired. Being present while they are still choosing how to fund care is what moves your name into the shortlist.
| Funding path | Typical lead time | What the family asks a provider |
|---|---|---|
| Sell the house, then move | 60 to 120 days from listing to proceeds | Can we hold an apartment, and is there a deposit or move-in fee? |
| Bridge loan or HELOC to move first | 2 to 6 weeks to close | How fast can she move in, and what does the first quarter cost? |
| Reverse mortgage to age in place | About 30 to 60 days including counseling | How many hours of care a week can the line of credit sustain? |
| Rent the house out to fund care | 1 to 3 months to place a tenant | Will the rent cover the monthly fee, and what if a unit sits empty? |
| Family member buys the house | 30 to 60 days | Can care start now while the sale to a relative is arranged? |
The reverse mortgage residency rule matters to you
A HECM reverse mortgage requires the home to stay the borrower's principal residence. If the last borrower lives away for more than 12 consecutive months for health reasons, the loan can become due (CFPB on moving out with a reverse mortgage). That makes reverse-mortgage families strong in-home care prospects and weaker residential prospects unless a spouse stays behind.
How do the three Mortgages+ offers work for care providers?
You can buy consented care leads in real time by ZIP and care type, hire Mortgages+ to run dedicated campaigns for your community or agency on a monthly retainer, or become a founding partner and buy leads at a 30% discount over time.
- Step 1
Real-Time Leads
Fund a prepaid balance, choose care types and ZIP codes, set a bid of at least $25 and a daily cap. Your wallet must hold at least 4 × your bid. The highest funded bid in the ZIP wins each lead exclusively and receives it in the dashboard and inbox the moment the family confirms their phone.
- Step 2
Joint Ventures
A monthly marketing retainer for campaigns built around your community or agency: landing pages, email to families researching equity options, social and content in your markets, with monthly reporting. Senior living is not a RESPA settlement service, so a success fee on move-ins (less retainer paid) may apply, structured with your counsel.
- Step 3
Partners
Founding partners pay a one-time partnership fee for a stake in the platform's growth and earn that value back inside the bidding system at a 30% discount on leads, plus featured placement and co-marketing kits.
Many operators start with Real-Time Leads in two or three ZIP clusters around their communities, measure tours booked, then add a Joint Venture for a new building or a census push. The full comparison sits on our care-provider partnership terms.
01 · Bid from $25 per lead
Real-Time Leads
Target assisted living, memory care, independent living or in-home care by ZIP code and pay from $25 per consented lead. Each lead shows the family's care type, timeline and home situation.
Add money & place a bid02 · We market for you
Joint Ventures
A monthly retainer funds campaigns aimed at families researching equity for care in your service area, with monthly reporting. Because senior living is not a settlement service, a success fee on closed business may apply, reviewed against anti-kickback rules if you bill federal programs.
Discuss a joint venture03 · Own a piece of the platform
Partners
Founding partners make a one-time partnership fee, then earn it back at a 30% discount on care leads, with featured placement on our senior funding content.
Become a partnerAny success-fee or revenue-share arrangement that requires state licensing, regulatory approval or a specific legal structure (for example, settlement-service providers covered by RESPA) must be handled independently by the partner, or the licensing, contracting and legal work needed to make it compliant will be billed in addition to the program fees.
What compliance rules apply to buying senior care leads?
Expect four layers: state licensing and placement-agency rules, elder-financial-abuse safeguards, privacy rules for any health details, and, if you bill Medicare or Medicaid, the federal Anti-Kickback Statute. TCPA consent governs how you call and text.
- TCPA: every lead carries the consent wording, timestamp, IP and user agent from the family's own tap. Call and text only the number that consented, honor stop requests immediately and keep the consent record with the lead (47 U.S.C. 227).
- Anti-Kickback Statute: paying for referrals of services reimbursable by a federal health care program can violate 42 U.S.C. 1320a-7b(b) (federal anti-kickback statute text). Mortgages+ prices per lead, for the lead itself, never per admission. Home health agencies that bill Medicare should still have counsel review any lead program (HHS OIG overview of fraud and abuse laws).
- State rules: assisted living, memory care and home care licensing vary by state, and several states regulate senior placement or referral agencies with registration and disclosure duties. Confirm your own obligations before you advertise.
- Elder financial safeguards: when the conversation turns to selling or borrowing against a parent's house, never steer the family to a specific lender or buyer and never accept a power of attorney or ask for account access. Point them to neutral resources such as the CFPB resources for older adults.
- Health details: the lead form asks only the type of care. Anything a family tells you later about diagnoses should be handled under your own privacy policies and HIPAA obligations where they apply.
How should you work a senior care lead once it arrives?
Call within five minutes, lead with the family's funding question rather than your amenities, book a tour or an in-home assessment on the first call, and follow a 14-day cadence that respects that adult children are often working full time.
The person who submits the form is frequently an adult child, not the future resident. They are juggling a job, a parent and a house. Your first call should solve one problem for them, and the problem they raised was money. Our senior living lead generation playbook goes deeper on scripts by care type.
- Step 1
Minute 0 to 5
Call. If no answer, send one text: your name, the community or agency, and a single question about timing.
- Step 2
Day 1
Second call at a different time of day. Email a one-page cost sheet that shows monthly fees, level-of-care pricing and what is included.
- Step 3
Day 3
Offer a tour or a free in-home assessment, with a weekend option for working family members.
- Step 4
Day 7
Share a neutral explainer on funding options, such as the CFPB reverse mortgage guide, and offer to talk through timing with their agent or lender.
- Step 5
Day 14
Final check-in. Ask permission to stay in touch monthly until the home question is resolved.
A useful opener: 'You mentioned your mom may need assisted living and the plan is to use the house. Most families we work with are deciding between selling first or moving first. Which way are you leaning?' That one question tells you the move-in window and whether the family needs a deposit hold, a short-term respite stay or nothing yet.
Which partners help care providers convert equity-funded families?
Elder-law attorneys, reverse mortgage specialists, real estate agents who handle senior moves and movers all touch the same family. Knowing who they are lets you answer the funding question without overstepping your license.
You are not a lender and should not act like one, but families will ask. Have neutral answers ready and know which specialists exist. Mortgages+ also runs categories for elder-law and estate-planning attorneys, for reverse mortgage specialists who serve older homeowners and for movers who handle downsizing moves. Families who want to understand the loan side can read our guide to using a reverse mortgage for long-term care.
Keep referral relationships clean
Swapping referrals with a lender or real estate agent for money or things of value can raise RESPA Section 8 issues on their side, and payments tied to residents can raise anti-kickback issues on yours. Co-market openly, refer on merit and pay only for marketing actually performed.
How does bidding on senior care leads work?
You fund a wallet, choose a category and ZIP codes, and bid what a lead is worth to you, from $25. The highest funded bid wins each matching consented request exclusively and pays its bid.
- Step 1
Create your account
Tell us your business, licenses and service area. It takes about three minutes.
- Step 2
Add money
Fund your wallet. To place a bid it needs at least 4 × the bid; you only ever spend what you load.
- Step 3
Choose category and ZIPs
Pick senior care leads, the ZIP codes or states you serve and a daily cap.
- Step 4
Place a bid from $25
Bid in $1 steps. The highest funded bid for the category and ZIP wins each lead; ties go to the earliest bid.
- Step 5
Win leads exclusively
Each consented, phone-verified request goes to one partner per category, by email and in your portal within seconds.
- Step 6
Tune as you go
Raise, lower or pause bids and change ZIP codes. You pay your bid only for leads you win.
A bidding example (illustrative)
Illustrative only: an assisted living operator targets 14 ZIP codes around two communities at a $55 bid with a cap of four leads a day, while a home care agency bids $30 in the same ZIPs. Both fund $1,500 balances, well above the 4 × bid minimum ($220 and $120). When a request in those ZIPs arrives, the operator's $55 bid wins it exclusively and pays $55; the agency wins a request only once the operator's daily cap is reached or its wallet can no longer cover the bid.
Compliance for senior living & in-home care partners
State licensing, elder-financial-abuse safeguards, HIPAA where health data is involved, and TCPA consent. Every Mortgages+ lead carries the consumer’s timestamped “Get Code” consent, the exact consent wording, IP and device. You pay for the lead itself, never for a closed transaction or a referral.
Senior living & in-home care leads: frequently asked questions
Are these leads from the future resident or a family member?
Either. The form is completed by whoever is researching, and it is often an adult child. The consented phone number belongs to the person who completed it.
Can I target memory care separately from assisted living?
Yes. The care-type answer on each lead lets you bid only on the categories you serve, including in-home care, assisted living, memory care and independent living.
Do you share leads with other communities?
No. Each lead is sold to one partner per category: the highest funded bid for the request's ZIP code wins it exclusively, and ties go to the earliest bid. A family never hears from two senior care providers via Mortgages+.
Is paying per lead allowed if we accept Medicaid waiver residents?
Per-lead pricing for the lead itself is the structure counsel generally prefers, but if you bill any federal health care program you should have your attorney review the arrangement under the Anti-Kickback Statute.
Will you tell families which community to choose?
No. Mortgages+ is a marketplace, not a placement agency. We deliver the consented request; the family chooses.
What is the minimum spend?
The minimum bid is $25 per lead. You set your own balance and daily caps and can pause at any time.
Can I bid on a whole state instead of individual ZIP codes?
Yes. Choose a whole state when you place a bid and it covers every ZIP code in that state, including ZIPs added later; you can remove individual ZIPs you don't serve. ZIP-level and state-level bids compete on price alone, and ties go to the earliest bid.
Who handles licensing and legal work for success fees or revenue sharing?
The partner does. Any success-fee or revenue-share arrangement that requires state licensing, regulatory approval or a specific legal structure (for example, settlement-service providers covered by RESPA) must be handled independently by the partner, or the licensing, contracting and legal work needed to make it compliant will be billed in addition to the program fees. Settlement-service providers such as lenders, title and escrow companies and real estate agents pay a flat marketing fee at fair market value, never a success fee tied to closings, and Real-Time Leads are always priced per lead delivered.
Many of the families you serve also need a loan for their own next move. point adult children toward a mortgage pre-approval when they are buying near a parent's new community.
Go deeper on senior care leads
 Senior Living Lead Generation That Starts With the HouseThe best senior living leads come from families already solving the funding question. Here is how to source, score and convert move-in leads tied to a home sale.
 What Home Care and Senior Living Leads Cost Per LeadOn Mortgages+ you set your own price: bids start at $25 per consented lead. Here is how to work out a bid ceiling from hours of care, margin and close rate.
Where these leads come from
See the page your future customers read
Homeowners find you through Paying for Senior Living With Home Equity: 5 Options, then request matched help with a verified phone and recorded consent.
Sources
Content reviewed November 18, 2026 against these authoritative sources.
- 1.Genworth and CareScout: Cost of Care Survey results for 2024
- 2.Medicare.gov: Long-term care coverage
- 3.CFPB: What happens if I need to move out of my home with a reverse mortgage?
- 4.Cornell LII: 42 U.S.C. 1320a-7b (Anti-Kickback Statute)
- 5.HHS OIG: Fraud and abuse laws
- 6.Cornell LII: 47 U.S.C. 227 (TCPA)
- 7.CFPB: Resources for older adults
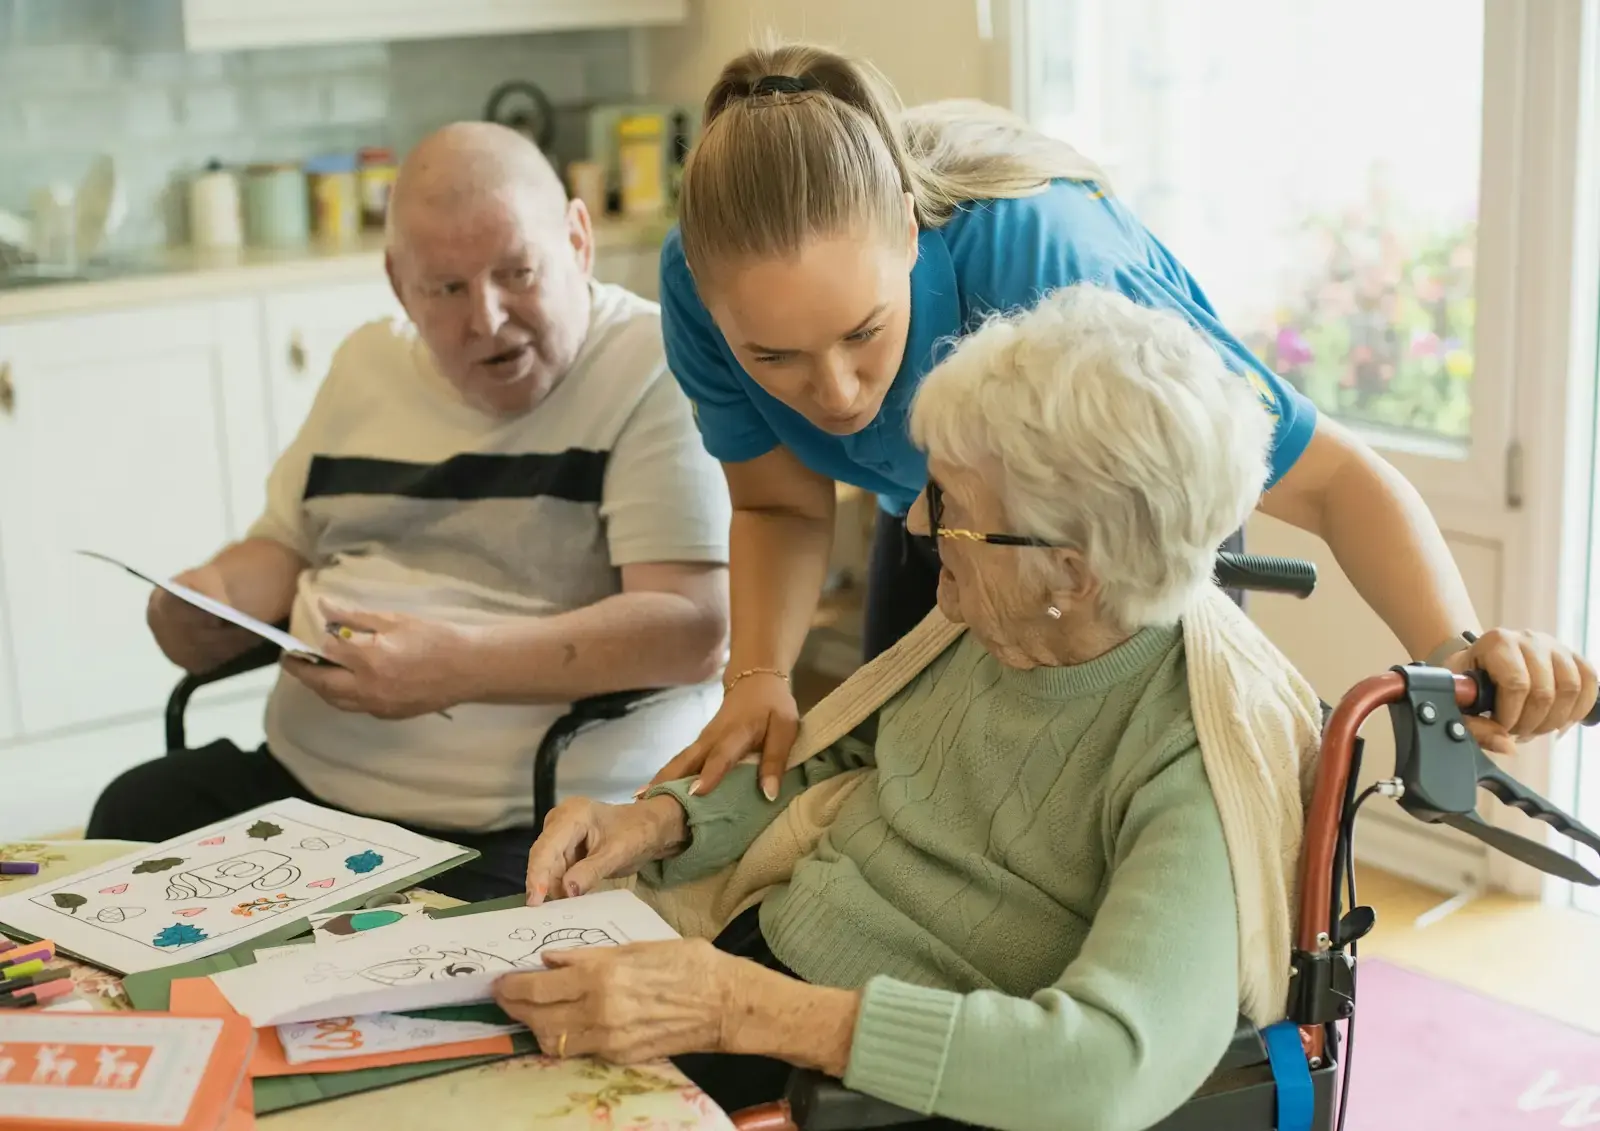
Photo: A caregiver sitting with an older couple by Age Cymru on Unsplash (Unsplash License).

Mortgages+ marketplace
Ready for senior care leads from the mortgage moment?
Create your account, add money and set your first bid in minutes. Or talk to us about a joint venture or a founding partnership.
Already a partner? Sign in to the partner portal. Prefer to talk first? See partnerships, joint ventures and investor options.