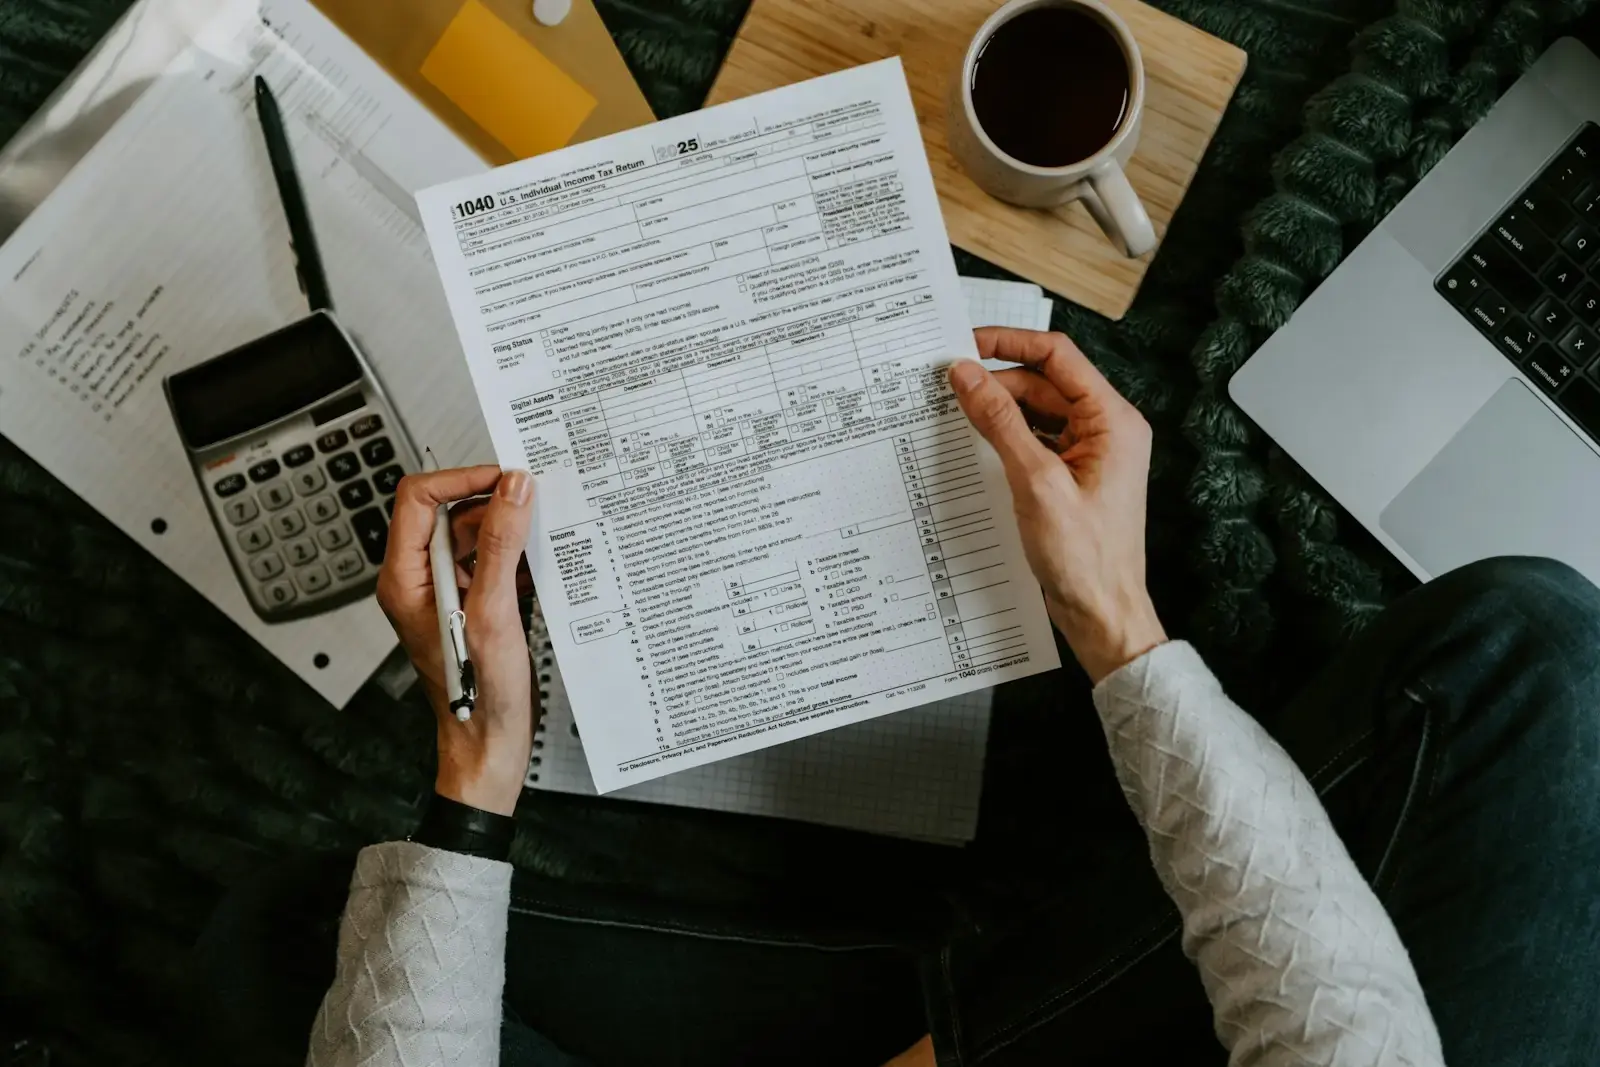
Divorce & family law partners · CDFA marketing ideas
CDFA Marketing Ideas Built Around the Marital Home
Strong CDFA marketing leads with the house: buyout analyses, refinance-readiness reviews, attorney workshops and consented leads from people deciding whether to keep it.
Certified Divorce Financial Analysts solve a problem most people do not know they have until the settlement is on the table. The marital home is where that problem is most visible, so it is the best place to start your marketing. Here are practical ideas, a sample deliverable and the compliance guardrails for each.
Key takeaways
- Lead with a tangible deliverable: a one-page buyout and refinance-readiness analysis.
- Attorneys and mediators are your best referral sources; give them a reason to send clients early.
- Do not accept payment from lenders or agents for referring clients; RESPA Section 8 applies to settlement-service referrals.
- If you are also an investment adviser, testimonials and endorsements fall under the SEC Marketing Rule.
Why should CDFA marketing lead with the house?
Because it is the decision clients worry about most and understand least. A clear answer on whether they can keep the home is the fastest way to show what a CDFA does.
Pensions, retirement accounts and tax basis matter just as much, but clients do not search for them at 11 p.m. They search for “can I keep the house in a divorce.” Meet that question with a specific promise, such as a buyout and refinance review in 48 hours, and the rest of the engagement follows. The divorce and family law partner page explains how Mortgages+ delivers those searchers as consented leads.
What marketing works best for a divorce financial analyst?
Content that answers the house question, referral relationships with attorneys and mediators, small educational workshops and paid leads from people already asking for help.
| Idea | Effort | Cost | What it proves to prospects |
|---|---|---|---|
| Buyout calculator on your site | Medium | Low | You can do the math they fear |
| Refinance-readiness review offer | Low | Your time | Whether keeping the home is realistic |
| Quarterly attorney lunch-and-learn | Medium | Low | You make attorneys' settlements stronger |
| Mediator co-hosted workshop | Medium | Low | You are neutral and practical |
| Plain-English blog on divorce taxes | High | Low | Depth beyond the house |
| Local search profile and reviews | Low | Free | Credibility nearby (mind the SEC Marketing Rule if you are an adviser) |
| Consented divorce and home leads | Low | From $25 per lead | Speed: you respond when they ask |
| Flat-fee co-marketing campaign | Low | Monthly retainer | Consistent presence in your market |
What should a CDFA buyout analysis show?
The home's value, the mortgage balance, the equity split, how the buyout will be funded and whether the keeping spouse qualifies for the new loan on their own income plus support.
A one-page deliverable is your best marketing asset because clients forward it to their attorney. Here is an illustrative example for a $480,000 home with a $260,000 mortgage, split 50/50.
| Line | Amount | Note |
|---|---|---|
| Appraised value | $480,000 | Non-lending appraisal with the agreed valuation date |
| Mortgage balance | $260,000 | From the latest statement |
| Equity | $220,000 | Before any selling costs or offsets |
| Buyout owed (50%) | $110,000 | Subject to other asset offsets |
| New loan needed | $370,000 plus closing costs | About 77% of value |
| Qualifying test | Housing payment about $2,900 | Compare to income plus documented support |
Fannie Mae can treat a buyout of a co-owner's interest under a written agreement as a limited cash-out refinance, if the home was jointly owned for at least 12 months and the buying spouse receives none of the proceeds (Fannie Mae Selling Guide). Ask the lender to confirm; that treatment can mean better pricing than a standard cash-out loan.
How should a CDFA build referral partnerships safely?
Exchange education and good work, not money for referrals. Refer clients to lenders and agents on merit and never accept payments tied to the loans or sales you send them.
- RESPA Section 8 bans giving or accepting anything of value for referring settlement-service business, which includes mortgage loans and real estate sales (12 U.S.C. 2607).
- Give clients two or three lender names, not one, and document why.
- If you are an investment adviser, paid endorsements and testimonials require disclosures under the SEC Marketing Rule (SEC).
- Follow the IDFA's code of ethics on objectivity and scope (IDFA).
- Attorneys cannot share fees with you, so frame the relationship around better outcomes for shared clients. Our page on lead generation ethics for family-law firms explains their rules.
How do you run a workshop that attorneys will send clients to?
Keep it educational, short and specific: 60 minutes on the house, retirement accounts and taxes, co-hosted with a mediator or attorney, with no pitch and a clear next step.
- Step 1
Pick one promise
“What happens to the house, the 401(k) and your taxes in a divorce” beats a general financial wellness talk.
- Step 2
Co-host
A mediator or attorney covers the legal process; you cover the numbers. Each of you invites your own network.
- Step 3
Teach the buyout math
Walk through one illustrative buyout, including the after-tax value of keeping a home with a large built-in gain.
- Step 4
Offer a review
End with an invitation to a 30-minute refinance-readiness review, booked by text or email with consent.
- Step 5
Respect confidentiality
Share nothing about attendees with anyone, but do send your co-host a short note on the topics people asked about.
Many attendees are not ready to hire anyone the night of the workshop. A consistent email sequence afterward, and a presence when they finally search for help, captures them later.
How should a CDFA measure marketing results?
Track cost per consultation and cost per engaged client by channel each month, and how many engagements came from each attorney or mediator.
Illustrative: a practice spends $800 on leads at $40 each (20 leads), books 6 consultations and engages 2 clients at $3,500 each. That is $133 per consultation and $400 per engaged client. Compare that against the hours you spend on workshops and lunches. Many CDFAs find that paid leads fill the calendar between referral waves, and that clients who arrive with a home question often hire them for the full settlement. When the client is weighing a later-life move or using equity in retirement, the guide to home equity in retirement planning is a helpful read to share.
Frequently asked questions
What is a CDFA?
A Certified Divorce Financial Analyst, a credential from the Institute for Divorce Financial Analysts for professionals who analyze the financial side of divorce settlements.
Can a CDFA accept referral fees from mortgage lenders?
No for payments tied to referring loans. RESPA Section 8 prohibits referral fees for settlement-service business.
What is a good first offer for CDFA prospects?
A short buyout and refinance-readiness review of the marital home, delivered within a few days.
Can a CDFA use client testimonials?
If the CDFA is an investment adviser, testimonials are allowed under the SEC Marketing Rule only with required disclosures and oversight. Others should follow state rules and the IDFA code.
How do CDFAs get leads from Mortgages+?
Fund a prepaid balance, select the divorce and family law category and your ZIPs, and bid from $25 per consented lead.
Before you finalize a buyout analysis, test a buyout with a single-income pre-approval so the refinance is real.
More for divorce financial analysts (cdfa) and family-law firms
 Divorce and Home Leads for CDFAs and Family-Law FirmsDivorce and home leads reach people deciding who keeps the house, who refinances and whether to sell. Bid from $25 per consented lead, or fund a flat-fee campaign.
 Divorce Attorney Lead Generation That Fits the Bar RulesDivorce attorneys can buy consented leads when the vendor does not recommend the firm, pricing is per lead with no fee sharing and the first contact answers a request.
Curious what the homeowner sees before they become your lead? Read our divorce & family law guide for homeowners.
Sources
Content reviewed November 18, 2026 against these authoritative sources.
- 1.Fannie Mae: Selling Guide B2-1.3-02: Limited Cash-Out Refinance Transactions
- 2.U.S. Code (Cornell LII): 12 U.S.C. 2607 (RESPA Section 8)
- 3.SEC: Investment Adviser Marketing
- 4.Institute for Divorce Financial Analysts: About the CDFA designation
Photo: Financial forms with a calculator and laptop by Kelly Sikkema on Unsplash (Unsplash License).

Mortgages+ marketplace
Start buying divorce and home leads today
Create an account, add money and place your first bid. You control categories, ZIP codes, caps and price.
Already a partner? Sign in to the partner portal. Prefer to talk first? See partnerships, joint ventures and investor options.